Unsecured lines of credit give you flexible borrowing with no collateral, but they usually cost more and cap out at lower limits. Secured lines trade pledged assets for lower rates and bigger credit lines. If you need smaller, short-term draws and want to avoid risking property, unsecured usually wins. If you need a large limit, have weaker credit, or qualify for an SBA-backed track, secured financing is often the better fit, as long as you understand the personal guarantee and lien terms first.
TL;DR:
- Unsecured lines of credit typically offer higher interest rates, smaller borrowing caps, and depend heavily on credit score and cash flow for approval.
- Secured lines provide larger limits and lower rates by requiring collateral such as real estate, inventory, or receivables, but risk asset seizure if default occurs.
- Fees, draw periods, and how payments are calculated can offset lower advertised APRs, making total costs anytime the key factor in choosing between secured and unsecured options.
- For short-term needs like cash gaps or emergencies, unsecured credit is faster and less risky, but for larger amounts, secured lines are often more suitable.
- Properly matching the credit facility to your purpose and thoroughly understanding terms and collateral requirements helps prevent costly surprises later.
Before picking a direction, it helps to see the trade-offs side by side. A line of credit, whether personal or business, is a revolving account: you draw what you need, pay interest only on that balance, and your available credit refills as you repay it, according to the Consumer Financial Protection Bureau.
An unsecured line of credit is revolving credit that does not require you to pledge an asset. Most personal lines of credit fall into this category, according to the CFPB, which distinguishes them from home equity lines of credit that are secured by your house. Lenders underwrite unsecured lines based on your credit score, income or business revenue, and time in business, and many business lines still require a personal guarantee even without formal collateral, per SBA guidance.
These lines work best for short-term, moderate needs rather than large capital projects.
The trade-off is cost and ceiling. Unsecured APRs run higher than secured alternatives, and limits tend to be lower because the lender has no asset to recover if you default. Heavy utilization of the line can also affect your credit score, so treat it as a buffer rather than a primary funding source. For more on practical day-to-day uses, see this breakdown of business line of credit uses.
A secured line of credit ties your available credit to a pledged asset, which the lender can claim if you stop paying; for a detailed look at these secured lending mechanics, see this overview of DSCR loans for investors. Common collateral includes real estate (as with a HELOC), business equipment, inventory, or outstanding receivables. Because the lender has recourse to a specific asset, secured lines generally support larger limits and lower rates than unsecured products, per SBA guidance.
Home equity lines of credit carry their own disclosure rules. Under Regulation Z, lenders must spell out the draw period, the repayment period, how minimum payments are calculated, and payment examples showing what happens if rates rise, based on Federal Reserve research into HELOC disclosure practices. Nearly all HELOCs carry variable rates, so your payment can increase even if your balance does not.
Asset-based business lines often require ongoing collateral monitoring and borrowing-base reporting, so ask how often the lender revalues the collateral and what triggers a limit reduction.
A lower advertised APR does not always mean a cheaper facility. Fees, draw-period length, and how minimum payments are calculated can offset the savings from a lower rate, a point Federal Reserve research on HELOC disclosures makes directly.
Statistic Callout: HELOCs generally carry variable interest rates, and the Federal Reserve’s HELOC disclosure research emphasizes that payment examples required under Regulation Z highlight how rising rates can increase a borrower’s payment beyond the initial quote.
A secured line that starts cheap can still end up costing more once draw-period interest-only payments convert to full amortization, or once a rate adjustment hits. Compare the full repayment schedule, not just the starting number.
Match the facility to the need, not the other way around. Walk through this before contacting a lender.
Ask every lender these questions before signing anything: What is the exact APR and is it fixed or variable? What fees apply at opening, annually, and at draw? How long is the draw period, and what happens when it ends? Exactly what collateral secures this line, and how is it valued? Is a personal guarantee required even if the line is secured by business assets? What happens on default, and what can be seized? Does the line renew automatically, and under what terms? Are there minimum draw or balance requirements? Are there covenants tied to revenue or financial ratios? Can the lender reduce my limit without notice?
Pro Tip: If a lender can’t clearly answer the collateral and default questions in plain language, treat that as a red flag and keep comparing offers.
For SBA-backed business borrowers, collateral rules shift at certain loan sizes. Under SBA 7(a) guidance, loans of $50,000 or less typically do not require collateral, while larger loans follow the lender’s written collateral policy, and a lender cannot decline solely for insufficient collateral. The 7(a) Working Capital Pilot also permits revolving lines against receivables and inventory, which suits timing gaps better than a term loan. Read more on SBA loan collateral rules and why lenders ask for collateral at all.
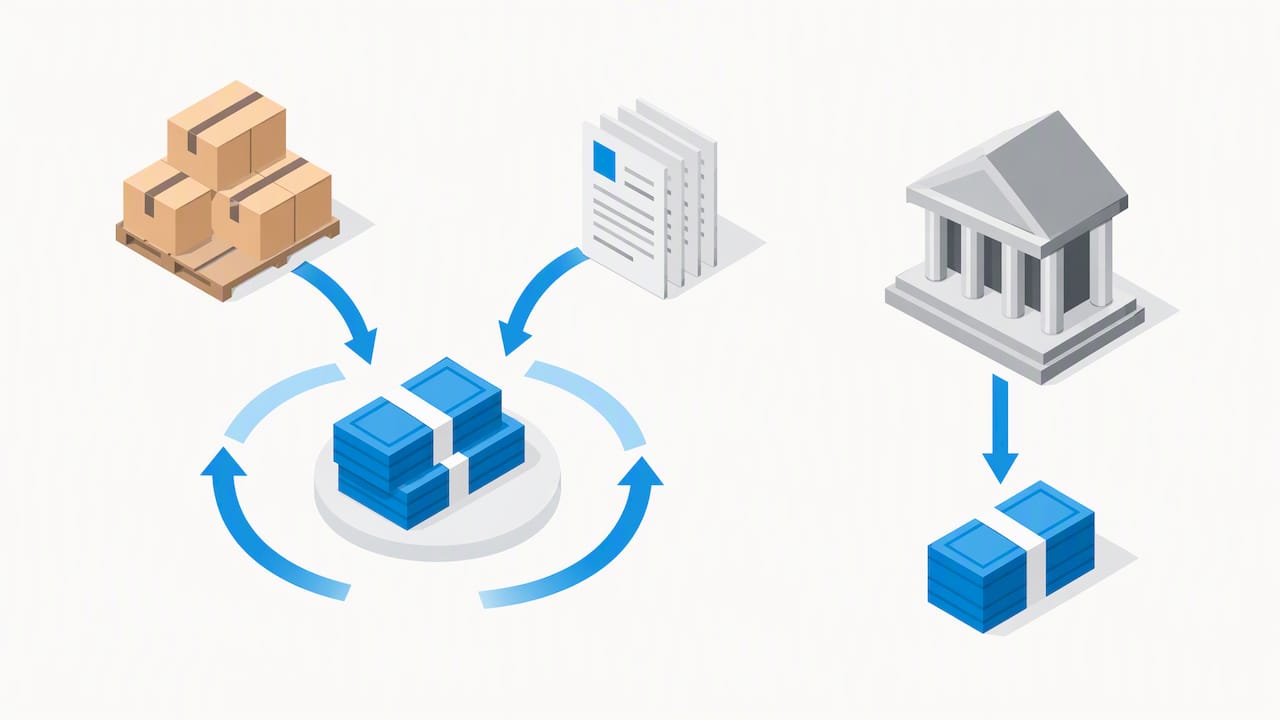
Fordham Capital connects small and medium-sized businesses to a network of banks and alternative lenders for SBA loans, lines of credit, and working capital, using a one-page application that does not affect your credit score.
This approach tends to fit:
Before applying, gather basic financials (recent bank statements, revenue figures) and, if you have them, details on any assets you’d consider pledging. Having both ready speeds up matching you to the right lender in the network.
The biggest mistake borrowers make is chasing the lowest headline rate instead of the terms that fit their cash flow. Read the draw and repayment disclosures closely, ask the questions above before signing, and remember that the cheapest line on paper can become the most expensive one in practice if the structure doesn’t match how you actually spend.
— Rob
Fordham Capital offers a streamlined application process with access to a network of banks and alternative lenders, providing approval decisions quickly, all without impacting your credit score or requiring collateral.
If you’ve read through the checklist above and know your purpose, amount, and timeline, you’re ready to apply. Have your recent bank statements and basic revenue figures on hand so the application moves quickly.
Start your application at Fordham Capital, and see what you qualify for before you commit to any lender.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Neither is universally better: unsecured debt avoids collateral risk but usually costs more and caps lower, while secured debt offers lower rates and higher limits in exchange for pledging an asset. The right choice depends on how much you need, what you’re willing to risk, and your credit profile, per SBA guidance.
A secured creditor has a legal claim on specific collateral and can seize that asset if you default. An unsecured creditor has no such claim and must pursue other collection methods, such as reporting to credit bureaus or taking legal action for repayment.
An unsecured loan is approved based on your creditworthiness alone, with no asset backing it, while a secured loan requires you to pledge property, equipment, or another asset as collateral. Secured loans typically carry lower rates and larger limits because the lender has recourse to that asset, according to the SBA.
A secured line of credit is a revolving credit account backed by collateral, such as a home in the case of a HELOC, or business equipment, inventory, or receivables for commercial lines. The pledged asset allows for higher credit limits and lower interest rates than an unsecured line, but it also means the lender can claim that asset if you default.
At Fordham Capital, we've made the application process straightforward and reassuring. Dive in and explore your financial options with confidence, knowing there's no impact on your credit score and no obligations. We review your details and offer customized solutions based on what you're looking for.