Yes, growing ecommerce brands typically need working capital, because sales, inventory buys, and payouts rarely land on the same calendar. You can close that gap in two ways: tighten operations like payout speed and inventory turns, or bring in targeted, non-dilutive financing while you fix the underlying timing. This guide walks through the metrics, the funding categories, and a practical route to fast approval through Fordham Capital.
TL;DR:
- Ecommerce brands with longer payout holds and slower inventory turns need flexible funding options like lines of credit or merchant cash advances to cover cash flow gaps.
- Monitoring metrics such as the cash conversion cycle, days inventory outstanding, and payout hold durations helps identify when cash shortfalls are likely to occur.
- Matching the right financing type—whether a revolving line of credit, inventory financing, or revenue-based funding—to your specific cash cycle minimizes costs and operational disruptions.
- Improving operational efficiency through faster reorder triggers, better supplier terms, and weekly cash forecasting can reduce reliance on external financing.
- Approval timelines vary from a few days for fintech options to several weeks for SBA-backed loans, making quick decision-ready documentation essential for urgent cash needs.
Working capital is current assets minus current liabilities: the cash, inventory, and receivables you can convert to pay bills within a year, minus what you owe in that same window. For a retail shop, that math is fairly stable. For an ecommerce brand, it swings hard because so much of the “asset” side is stuck in places you cannot touch quickly.
Inventory sitting on a container ship counts as an asset on paper, but it cannot pay a supplier invoice due next week. Prepaid ad spend behaves the same way: you have committed the cash, but the sales it generates might not arrive for a month. Marketplace payout holds and returns reserves add another layer, since platforms often withhold a portion of revenue against future refunds or chargebacks.
Payout rhythms vary by channel too. A direct-to-consumer store using a payment processor might see funds in two days. A marketplace seller might wait two weeks, with a chunk held back entirely during a return window. Say a brand ships $50,000 in goods in a single week: if $20,000 of that comes through a marketplace with a fourteen-day hold and the rest through instant-payout channels, the business is effectively financing that $20,000 out of pocket until the hold clears.
Misjudging this timing creates predictable problems:
None of this means the business is unprofitable. It usually means the cash cycle and the sales cycle are out of sync.
Once you accept that timing is the problem, you need numbers that show exactly where the gap sits. A handful of formulas cover almost everything:
Ecommerce benchmarks vary by product category and channel mix. A fashion brand carrying seasonal inventory runs a longer DIO than a consumables brand with fast repeat purchase cycles. One resource on ecommerce working capital management suggests a healthy current ratio in the range of roughly 1.5 to 2.0 and a quick ratio near 1.0 to 1.5, though the right target depends heavily on how concentrated your sales are on marketplaces with longer disbursement cycles versus direct channels that pay out faster.
Monthly financial statements catch these problems too late. A brand that only reviews cash position once a month can go three or four weeks before noticing a shortfall building, by which point a reorder deadline or ad budget has already been missed. A practitioner guide on fixing ecommerce working capital recommends a weekly cash cadence instead, mapping each sales channel separately so a marketplace hold does not get averaged away by faster-paying channels.
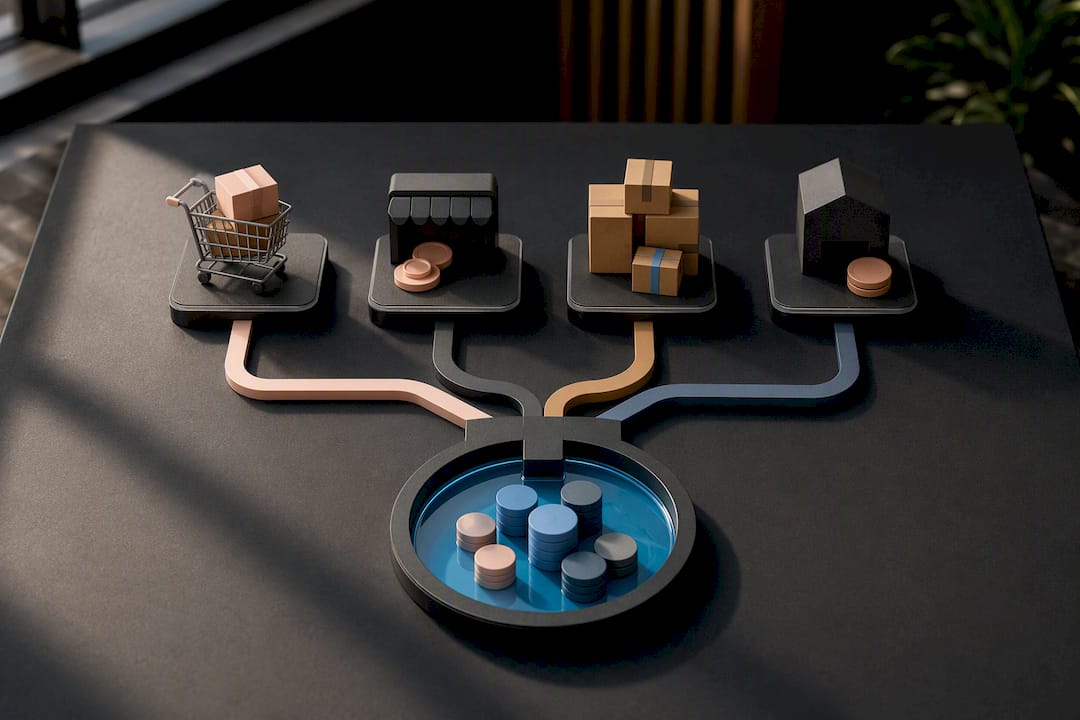
Pro Tip: Keep trapped inventory (goods in transit or awaiting customs clearance) in a separate line of your cash forecast rather than folding it into “available” stock, since treating it as spendable liquidity is the fastest way to misjudge a cash gap.
Working capital financing is not one product. Each category solves a slightly different timing problem, and matching the tool to the job matters more than chasing the lowest headline rate.
For a broader rundown of speed-focused options, see this comparison of fast business funding types.
One warning that applies across nearly every category: a factor rate is not an APR. A factor rate of 1.2 on a $10,000 advance means you repay $12,000 total, but the true annualized cost depends entirely on how fast that $2,000 is collected. A six-month repayment and a two-month repayment carry wildly different effective APRs for the same factor rate, and not every lender discloses that conversion clearly, so ask for it directly before comparing offers.
Picking the right product starts with matching it to your actual cash cycle rather than defaulting to whatever a lender pitches first.
Before applying, ask lenders directly: what triggers a repayment draw, how are refunds and chargebacks treated against the balance, and how frequently do you need updated bank or platform statements? These answers reveal more about real cost and fit than the rate alone.
Match the capital to the job. Inventory financing tied to a purchase order works well for a specific reorder. A revolving line of credit suits ongoing marketing spend that needs to flex with campaign performance. A seasonal spike calls for capital that can be drawn fast and repaid quickly once the peak sales period ends, rather than a long-term loan that outlives the need. Our guide on why working capital matters for growth covers this matching process in more detail.
Have these ready before you apply: three to six months of bank statements, payment processor or marketplace payout reports, current inventory value, and a simple cash forecast. Lenders move faster when the numbers are already reconciled.
Financing solves a timing problem, but operational changes shrink the size of the problem itself, which often means borrowing less and less often.
On inventory, set par levels for your top SKUs so reorders trigger automatically instead of reactively, and use staggered draws where a supplier is paid a deposit upfront and the balance on shipment rather than the full amount at once. SKU rationalization, cutting slow-moving products that tie up cash without turning, frees capital faster than almost any other single move. Inventory management guidance points to point-of-sale and forecasting tools as a practical way to catch slow turns before they become a cash drain.
On marketing and sales, prioritize payout channels with faster disbursement when cash is tight, and align campaign spend to when inventory is actually in stock rather than running ahead of supply. Build in a spend throttle: a rule that cuts ad budget automatically if cash coverage drops below a set number of weeks. A practical rollout playbook for ecommerce growth covers how to plan content and campaign cadence around operational capacity rather than purely around demand signals.
On suppliers and payments, negotiate net-30 or net-60 terms where possible instead of paying upfront, and where a vendor insists on prepayment, ask whether a portion can convert to invoiced billing once you have a payment history with them. Every extra week of supplier terms is effectively free working capital.
On forecasting, build a weekly cash model rather than relying on monthly statements, with finance, operations, and marketing working off the same calendar so a planned ad push and an inventory reorder never compete for the same cash at the same time. The step-by-step working capital plan for ecommerce recommends mapping each channel’s cash curve separately and building simple scenario playbooks: what happens to cash position if a campaign underperforms, or if a shipment is delayed by three weeks.
Pro Tip: Tie every inventory draw to a supply-chain milestone (deposit at order confirmation, balance at shipment) instead of paying in full upfront. It reduces both the amount of capital tied up at any moment and the forecasting noise around when it frees up.
A few signals reliably indicate it is time to bring in outside capital rather than keep patching operationally: repeated weekly shortfalls that a forecast keeps flagging, a supplier discount or bulk deal you cannot take advantage of because cash is tied up elsewhere, or a seasonal spike on the calendar that your current cash position cannot cover without delaying reorders.
Timelines vary widely by product type:
You can speed any of these up by having clean, reconciled bank and payment processor statements ready, along with a simple inventory forecast showing what you plan to order and when. Underwriting also differs by lender type: banks generally weigh trade exposure and receivables quality heavily, per Federal Reserve survey data showing stronger approval odds for firms with low trade exposure, while fintech lenders often weigh recent bank cash flow and sales velocity more heavily than credit history alone.
Comparing offers across categories only works once you translate every pricing shape into the same terms. Some lenders quote interest plus fees, some quote a flat factor rate, and some quote a revenue-share percentage, and none of these are directly comparable at face value.
Repayment timing is the hidden variable that changes everything. Say a $10,000 advance carries a 1.15 factor rate, meaning $11,500 total repayment. If that is collected over three months, the effective annualized cost is meaningfully higher than the same factor rate collected over eight months, because the same dollar amount of fee is being paid back over a much shorter window. Always ask a lender to state the term length alongside the factor rate before comparing it to a line of credit’s stated interest rate.
Watch for these common fees when reviewing an offer:
Satisfaction and disclosure practices differ meaningfully by lender type. Federal Reserve research on small business credit found that online lenders show mixed approval and satisfaction patterns compared to banks, with applicants often citing higher costs and less favorable repayment terms. That gap makes it worth asking any non-bank lender directly for an APR-equivalent figure rather than accepting a factor rate at face value.
Speed and simplicity matter most when a cash gap is already tightening a reorder deadline. Fordham Capital built its process around that reality: a one-page application, access to a network of banks and alternative lenders, and approvals that can come back within 24 hours. That structure fits the ecommerce timing problem described throughout this guide, where a two-week marketplace payout hold or a missed reorder window can cost more than the financing itself.
Fordham Capital is known for its focus on fast, non-dilutive ecommerce funding solutions. For an ecommerce brand weighing a working capital loan against a line of credit against inventory financing, that scale of lender access means the underwriting can be matched to the actual job, whether that is bridging a payout hold, funding a seasonal inventory buy, or covering a marketing push ahead of a launch, without the multi-week process that traditional bank underwriting often requires.
Because Fordham Capital operates as a connector rather than a single lender, the approval process does not hinge on one institution’s appetite for ecommerce risk. That network access, paired with a process built to avoid unnecessary credit impact, is the practical advantage for a seller who needs a decision quickly and cannot afford weeks of back-and-forth paperwork.
— Rob
If the timing gaps in this guide sound familiar, whether it is a marketplace payout hold, a seasonal inventory buy, or a marketing push that needs cash before revenue catches up, the application process is designed to provide quick answers without a hard credit inquiry.
Before applying, have your last three to six months of bank statements, a current inventory snapshot, and a simple revenue summary ready. Fordham Capital’s process typically works like this:
Start the application for SBA loans, lines of credit, and working capital to see what you qualify for before your next reorder deadline hits.
Approval for a loan that size depends heavily on lender type, with SBA-backed programs and banks generally requiring strong revenue history, collateral, and extensive documentation, while alternative lenders may weigh recent cash flow more heavily. Federal Reserve survey data shows banks are more likely to approve applications from firms with low trade exposure, so a clean financial history matters more as loan size grows.
Ecommerce remains a viable business model for sellers who manage cash timing carefully, since the operational challenge is less about demand and more about matching inventory and marketing spend to when cash actually arrives. The core issue explored throughout this guide, trapped liquidity from payout holds and inventory in transit, is manageable with the right forecasting cadence and financing mix.
Neither extreme is ideal: too little net working capital risks missed reorders and late supplier payments, while too much often means cash is sitting idle instead of funding growth. The right level depends on your cash conversion cycle and how quickly you can turn inventory and collect payouts across your specific sales channels.
Ecommerce businesses generally need enough working capital to cover the gap between paying suppliers and collecting sales revenue, since inventory purchases, prepaid marketing, and payout holds all require cash before revenue fully arrives. How much capital depends on your product category, sales channel mix, and how long your cash conversion cycle runs.
At Fordham Capital, we've made the application process straightforward and reassuring. Dive in and explore your financial options with confidence, knowing there's no impact on your credit score and no obligations. We review your details and offer customized solutions based on what you're looking for.